Buying Business Property in New Jersey: Fall 2026 Guide
Buying Property for a Business in New Jersey: What to Consider in Today’s Fall 2026 Market
Buying property for your business in New Jersey can give you more control over your location, occupancy costs, and long-term plans. But Fall 2026 calls for careful financial planning. Interest rates, property type, zoning, operating expenses, taxes, environmental considerations, and your company’s future space needs should all be reviewed before you make an offer.
For a business owner, the right property is not simply one that looks good or sits in a convenient location. It needs to support how your business operates today while making financial sense for the years ahead.

What Is the New Jersey Market Like in Fall 2026?
New Jersey business owners are entering the fall with a mixed economic picture.
Rutgers University’s Summer 2026 RECON forecast projects New Jersey real GDP growth of approximately 0.9% in both 2026 and 2027, while employment growth is expected to remain relatively modest. That points to a business environment where careful budgeting and realistic growth assumptions matter.
Financing also deserves close attention. On September 16, 2026, the Federal Reserve raised its target federal funds rate by 0.25 percentage point to 3.75% to 4.00%. The Fed cited continued economic growth alongside inflation that remains above its goal.
That does not mean buying commercial property is the wrong move. It does mean buyers should run the numbers based on current financing terms rather than assumptions from earlier in the year.
The picture also differs by property type. For example, CBRE reported that New Jersey office leasing improved during the second quarter of 2026, but volume was still 21% below the five-year quarterly average. Smaller office requirements continued to account for much of tenant demand.
For a business owner, those differences may create opportunities, but property type, location, condition, and intended use need to be considered separately.
1. Start With How Your Business Will Actually Use the Property
Before comparing buildings, write down exactly what the business needs.
Consider:
The amount of usable space you need now
Expected space needs over the next five to ten years
Parking requirements
Delivery and loading access
Visibility from major roads
Customer access
Employee access
Storage requirements
Office, showroom, retail, warehouse, or production space
Building systems needed for your type of operation
Buying too much space can leave your business paying for square footage it does not need. Buying too little could create another real estate decision sooner than expected.
Look at the property through the lens of your daily operations rather than concentrating only on the purchase price.
2. Compare the True Cost of Buying With Leasing
A mortgage payment is only one part of commercial property ownership.
Your financial review should account for:
Down payment
Loan payments
Property taxes
Building insurance
Utilities
Repairs and maintenance
Capital improvements
Common-area expenses, if applicable
Legal and accounting costs
Environmental inspections
Property inspections
Closing costs
Future building system replacements
It is helpful to compare several years of estimated ownership costs against what the company would spend leasing a suitable property.
Owning may offer long-term benefits, but the property should not place unnecessary pressure on the cash the business needs for payroll, inventory, equipment, marketing, and other operating expenses.
3. Review Financing Before Touring Too Many Properties
Commercial financing can work differently from a standard residential mortgage, so speaking with a commercial lender early can help you understand your realistic purchase range.
One financing option for qualifying small businesses is the SBA 504 loan program. According to the U.S. Small Business Administration, the program offers long-term, fixed-rate financing for qualifying major fixed assets, including the purchase, construction, or renovation of buildings and land.
The SBA also announced in July 2026 that eligible borrowers can combine 504 financing for up to $10 million in SBA-backed financing, subject to program requirements.
Not every business or transaction will qualify, so a lender, accountant, and financial advisor should review the available options with you.
4. Verify Zoning Before Committing to a Property
A building may look perfect and still not be approved for the way you intend to use it.
New Jersey municipalities establish their own zoning ordinances. These rules can affect permitted business activities, signage, parking, setbacks, building height, alterations, and other property uses.
The State of New Jersey recommends contacting the local zoning officer to confirm whether a property is suitable for the proposed business use and whether planning, zoning, or land-use approvals may be required.
Do this before assuming that a property's previous use guarantees approval for yours.
Questions to ask include:
Is my intended business use permitted?
Are additional approvals required?
Does my planned signage comply?
Is the existing parking sufficient under local requirements?
Are renovations or additions permitted?
Are there restrictions that may affect future expansion?
5. Understand New Jersey Property Taxes
Property taxes can make a meaningful difference in the long-term cost of owning commercial real estate.
New Jersey real property is generally taxed based on assessed value. The New Jersey Division of Taxation explains that real property assessment is tied to property value under state property-tax law, with assessment practices administered locally and through county tax boards.
Before purchasing, review:
Current annual property taxes
Property assessment
Local tax rate
Prior assessments
Recent reassessments
Comparable commercial assessments
Whether a change in ownership or improvements could affect future costs
Do not base the ownership budget solely on the seller’s current tax bill. Ask your attorney, accountant, and appropriate local tax professionals how taxes may apply to your specific transaction.
6. Do Not Skip Environmental Review
Environmental due diligence can be particularly important when purchasing commercial, industrial, manufacturing, automotive, dry-cleaning, warehouse, or previously developed property.
New Jersey has specific environmental requirements that may apply to certain commercial and industrial sites. Under the state’s Industrial Site Recovery Act, certain industrial establishments may have remediation obligations associated with a transfer or cessation of operations.
NJDEP also notes that environmental inquiries conducted before acquisition can be important when evaluating potential contamination and certain liability protections.
Depending on the property, your attorney or environmental professional may recommend a Phase I Environmental Site Assessment and additional investigation.
7. Inspect the Building, Not Just the Business Potential
Commercial repairs can become expensive quickly.
A professional property inspection should assess the physical condition of the building and identify concerns that may affect your purchase decision or operating budget.
Pay particular attention to:
Roof condition and remaining life
HVAC systems
Electrical capacity
Plumbing
Structural components
Drainage
Fire protection systems
Elevators, if applicable
Parking surfaces
Loading areas
Exterior condition
Accessibility features
Code-related concerns
For specialized buildings, bring in professionals who understand the intended use.
A less expensive property that requires major roof, electrical, HVAC, or structural work may ultimately cost considerably more than a higher-priced property in better condition.
8. Think About Location From a Business Perspective
Location means something different for every company.
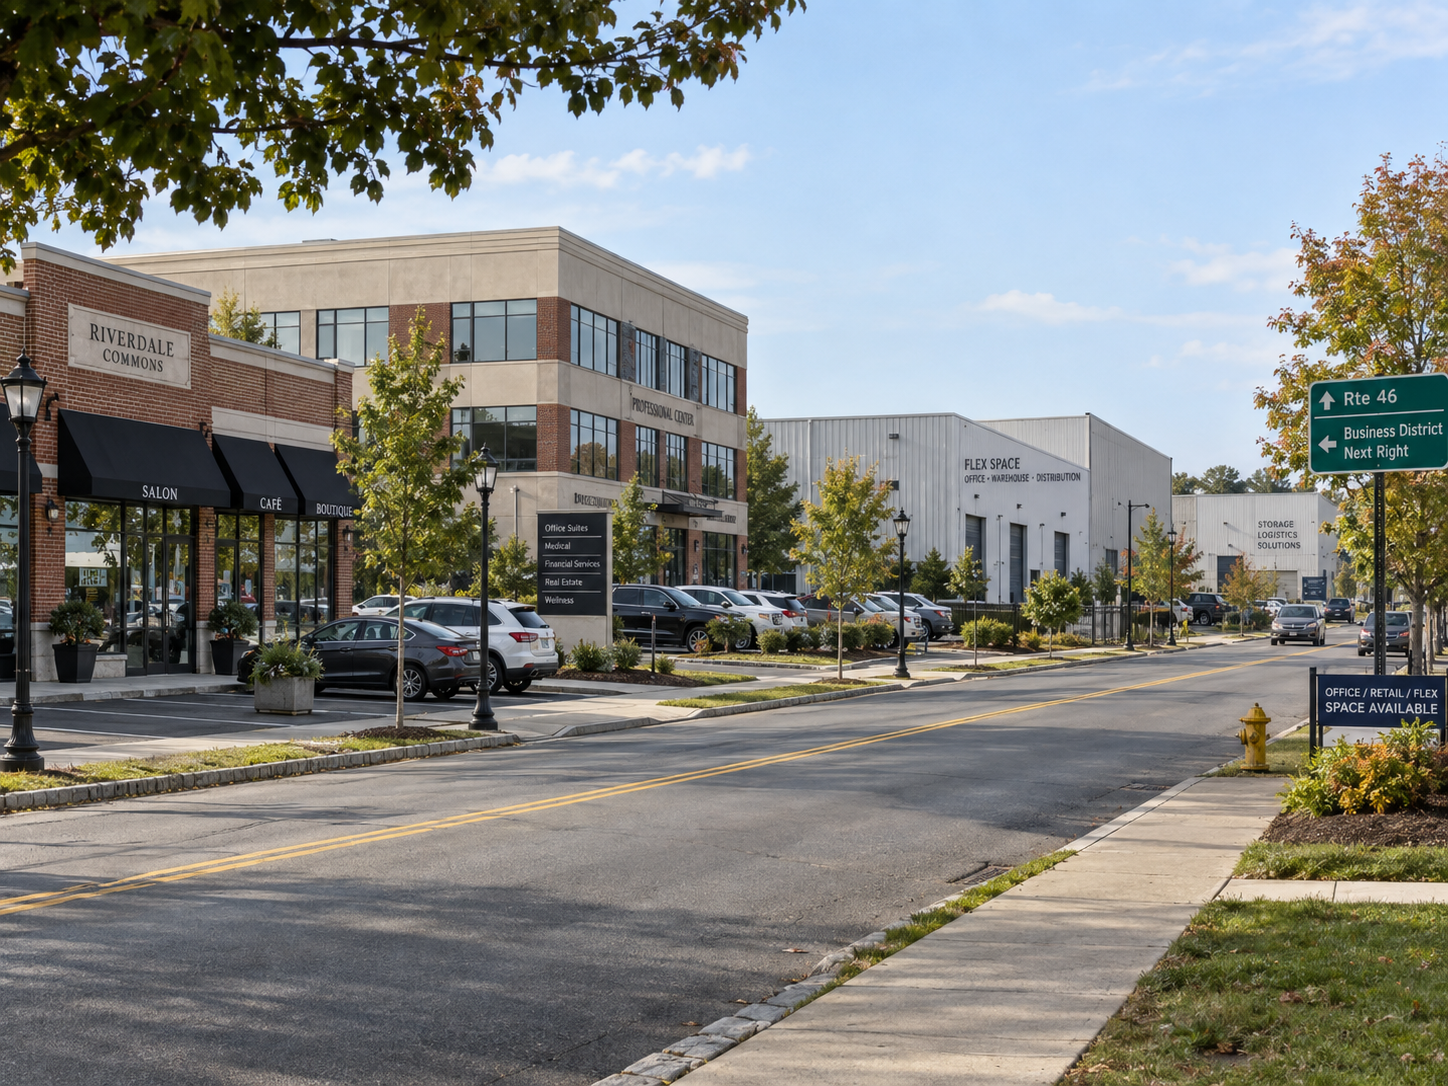
A retailer may prioritize visibility, parking, and customer access. An office-based company may value transportation connections and nearby services. A distribution or service business may place more weight on highway access, loading areas, vehicle circulation, and proximity to customers.
New Jersey offers very different commercial settings across Union, Morris, Middlesex, Somerset, and Essex Counties. Even neighboring municipalities can have different zoning regulations, tax structures, transportation access, available inventory, and redevelopment plans.
Ask yourself one practical question:
Does this location make operating my business easier or harder?
That answer can sometimes be more valuable than choosing a property simply because the asking price appears attractive.
9. Consider What Happens If Your Business Changes
Commercial property is a long-term commitment.
Think ahead about what could happen if:
Your company grows
Your company needs less space
You sell the business
You relocate
You want to rent part of the property
The building needs major improvements
Your operating requirements change
A property that gives the business reasonable flexibility may be easier to own over time.
Your attorney should also review how the property will be held, any entity structure involved, ownership agreements, and what happens to the real estate if the operating business is later sold.
10. Build the Right Team Before You Make an Offer
Commercial transactions can involve several professionals, and getting them involved early can help you identify concerns before they become expensive problems.
Depending on the property and transaction, your team may include:
A real estate professional familiar with the local commercial market
Commercial lender
Real estate attorney
Accountant or CPA
Building inspector
Environmental professional
Engineer or architect
Insurance professional
Municipal zoning officials
Good information gives you a stronger basis for deciding whether a property fits both the business and the budget.

Is Fall 2026 a Good Time to Buy Business Property in New Jersey?
There is no single answer for every business.
Fall 2026 includes higher borrowing costs than some buyers may prefer, moderate projected New Jersey economic growth, and property conditions that vary considerably by sector. At the same time, businesses with steady cash flow, a long-term need for space, and access to suitable financing may find ownership worth considering.
The better question is whether a particular property at a particular price works for your business under realistic financing, tax, repair, and operating assumptions.
That requires looking beyond the listing price and examining the complete cost and practical value of ownership.
Ready to Talk About Business Property in New Jersey?
If purchasing property is part of your business plan, having clear local information can make the search much more manageable.
I’m Christine Cederquist with Realty ONE Group, and as a lifelong New Jersey resident, I understand how much location, property condition, access, local amenities, and municipal requirements can matter in a real estate decision.
Thinking about purchasing property for your business in Union, Morris, Middlesex, Somerset, or Essex County? Let’s talk about what you need, what properties are available, and which options fit your plans.
Ready to talk about your selling goals? Let’s connect and discuss the next step for your home.
Christine Cederquist
Realty ONE Group
Phone: +1 908-380-3555
Email: CederquistRealty@gmail.com
This article is for general informational purposes and is not legal, tax, environmental, lending, or financial advice. Consult qualified professionals regarding your specific property and transaction.
FAQs
What should I check before buying commercial property in New Jersey?
Review zoning, financing, property taxes, building condition, environmental history, insurance expenses, access, parking, and whether the space supports your current and future operations.
Can an SBA loan be used to purchase commercial real estate?
Qualifying businesses may use SBA 504 financing for eligible fixed assets such as commercial buildings, land, construction, and certain renovations. Eligibility and occupancy requirements apply.
How do I know whether my business is allowed at a specific New Jersey property?
Contact the municipality’s zoning officer and confirm that your intended use is permitted. You should also determine whether zoning, planning, building, signage, or other approvals will be required.
Should I order an environmental assessment?
It may be appropriate, particularly for commercial and industrial sites with prior uses that could involve contamination. Your attorney and environmental professional can advise you on the appropriate level of review. New Jersey also has specific requirements affecting certain industrial properties.